Chrome-icon-sc
It looks like you’re on an old version of Chrome… Update your browser to attend this event.
For help updating, click here →
It looks like you’re on an old version of Chrome…
For help updating, click here
Chrome-icon-sc
It looks like you’re on an old version of Safari… For help updating, click here.
It looks like you’re on an old version of Safari…
For help updating, click here
Edge-icon-sc
It looks like you’re on an old version of Edge… Update your browser to attend this event.
It looks like you’re on an old version of Edge…
For help updating, click here
Edge-icon-sc
Firefox-icon-sc
It looks like you’re on an old version of Firefox… Update your browser to attend this event.
For help updating, click here →
It looks like you’re on an old version of Firefox…
For help updating, click here
Firefox-icon-sc
It looks like you’re using Opera… To attend, you’ll need Chrome or Firefox
Learn more in the Help Center →
It looks like you’re using browser we do not support… To attend, you’ll need Chrome or Firefox
Learn more in the Help Center →
Tortoise-icon
It looks like your internet is a little slow right now…
  • Check your connection
    Move closer to your router, connect to a faster network, or plug in via ethernet.
  • Check your computer
    Close extra browser tabs, quit other applications, or restart your computer.
  • Try our other tips
    When all else fails, contact us or visit our Help Center for more information.
Enter Webinar →
Learn more in the Help Center →
Edit Logo
Logo Image
Recommended size: square or rectangle at least 32px tall.
1782313682-d847b219b570c41e
Change image...
Delete
Logo Text
Required if you have no logo image. Optional if you have an image.
Link Logo to URL
PRO
Link the landing page logo back to your website. Requires Pro Plan or above.
Cancel
1782313682-d847b219b570c41e
, you’re registered for this webinar ! Manage registration → Not ? Click here

When the IRS Files for You: Substitutes for Return, the ASFR Pipeline, and the Replacement Strategy

Wednesday, December 2, 2026 · 1:00 p.m.  |  Eastern Time (US & Canada) (GMT -5:00)

Add to calendar
Reserve Your Spot
First Name*
Last Name*
Your Email*
Phone Number*
State*
Company*
Job title*
What type of credit do you want to earn? *
State Bar Number*
What jurisdiction are your requesting CLE for? *
PTIN*
Please add P followed by your 8 digit PTIN
Marketing Permission
Want to stay updated on the people, ideas, and insights shaping your industry? We promise not to spam you.
To register this webinar, you have to check this box.
✓ Yes, I consent to receiving emails*
Presenter
1780501925-a78be6ea6bfac47c
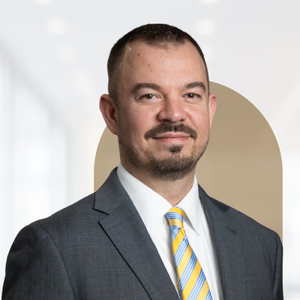
Matt Eddleman
EA
Matt Eddleman brings more than two decades of professional experience in tax controversy, accounting, financial planning, and small business management to Frost Law's Tax Compliance team.
About
Program Field of Study: Taxes | Federal Tax Law Topics/Federal Tax Related Matters
Program Level: Intermediate
Who Should Attend: CPAs, Enrolled Agents, tax preparers, attorneys
Credits: 1 CPE | 1 CE
Advanced Preparation: None
Prerequisite: None
IRS Program Number: JWRXB-T-00046-26-O

When a taxpayer stops filing, the IRS eventually stops waiting. Under IRC §6020(b), the Service can prepare a substitute for return (SFR) from third-party information returns. Its automated program builds those returns on assumptions that routinely overstate the liability: single or married-filing-separately status, no dependents, no business expenses, and missing basis. This episode follows the SFR from the first CP59 notice through the statutory notice of deficiency, assessment, and collection, and explains what remains available at each stage. It covers:

- the statute-of-limitations, penalty, refund, and collection-statute consequences of the
- SFR and of the replacement return;
- the joint-filing election after an SFR;
- the 90-day Tax Court trap;
- audit reconsideration;
- the limits of Collection Due Process;
- when filing a replacement return creates more exposure than it removes.
Agenda
  • Distinguish §6020(a) and §6020(b) returns and identify the elements of a valid SFR under Treas. Reg. §301.6020-1(b).
  • Trace the notice sequence from CP59 through CP3219N, and identify the response window and remedy at each stage.
  • Identify the computational assumptions that cause ASFR assessments to overstate liability.
  • Apply §§6501(b)(3), 6651(g)(2), 6511, and 6502 to determine the statute, penalty, refund, and collection-statute consequences of an SFR and of a replacement return.
  • Select the appropriate remedy (Tax Court petition, audit reconsideration, or CDP) based on case posture.
  • Evaluate when a replacement return creates new exposure: increased deficiencies, new assessments, criminal risk, and loss of bankruptcy discharge.
Share
COPY
All ALFi webinars