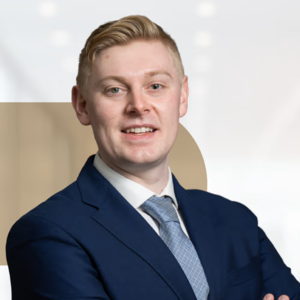
Robert Braland serves as a Senior Associate in the Tax Controversy and Tax Advisory practice groups at Frost Law. He earned his B.A. at Salisbury University in 2018. Robert then went to the University of Baltimore School of Law where he secured his Juris Doctor (J.D.) in 2021 and a Master of Laws (LL.M.) in Taxation in 2023. He joined Frost Law in 2023.
Before his tenure at Frost Law, Robert gained experience at the University of Baltimore Low-Income Taxpayer Clinic, advocating for taxpayers before the IRS, state tax authorities, and the United States District Court. He is an active member of the Maryland tax community, including serving on the MSBA Taxation Section Council. During his time with the Council, he has served as Co-Editor for Maryland Taxes, promoting the digital publication of the book for section members, as well as the Maryland Tax Practitioner’s Handbook.
Beyond his professional commitments, Robert is deeply involved in the Annapolis community. He holds a position on the board of Live Arts Maryland. In his leisure time, Robert enjoys everything the Chesapeake Bay has to offer.
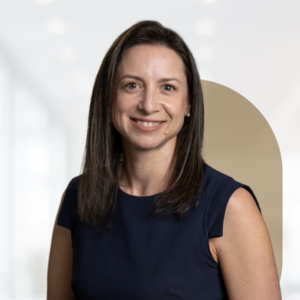
Rebecca Sheppard
Rebecca Sheppard is a Partner at Frost Law with extensive experience representing clients before the IRS and state taxing authorities. She advises on audits, appeals, and tax litigation, focusing on employment tax and the Employee Retention Credit. Rebecca is known for her practical, innovative approach to controversy work and her ability to translate complex tax issues into actionable guidance for practitioners. She regularly speaks on tax procedure and controversy topics to professional audiences. She is a member of the Maryland State Bar Association’s Taxation Section Council.
About
Program Field of Study: Taxes
Program Level: Basic
Who Should Attend: CPAs, Enrolled Agents, tax preparers, attorneys
Credits: 1 CPE | 1 CE
Advanced Preparation: None
Prerequisite: None
IRS Program Number: JWRXB-T-00039-26-O
This program provides a practical overview of how the Comptroller of Maryland examines income tax and sales and use tax returns, and how practitioners can protect their clients at each stage. Attendees will review the Comptroller's statutory examination authority under the Tax-General Article, the substantiation and limitations rules that govern income tax audits (including the treatment of federal adjustments), and the recordkeeping, sampling, and factor-computation rules that drive sales and use tax audits. The session walks through the mechanics of a Comptroller field audit from initial contact to closing conference, the assessment process and the presumption of correctness, interest and penalty exposure, and responsible-person liability.
Agenda
Identify the Comptroller of Maryland's statutory authority to examine returns, compel records and testimony, and use sampling techniques in sales and use tax audits. Apply the limitations periods governing Maryland income tax assessments, including the three-year general rule, the one-year rule following a timely reported federal adjustment, and the exceptions that remove the limitations bar.
Describe the recordkeeping obligations imposed on vendors under the Tax-General Article and COMAR, including the four-year retention period and requirements for electronic records.
Explain how the Comptroller computes tax when records are missing, the presumption of correctness attached to factor-based assessments, and the scope of responsible-person liability for sales and use tax.
Outline the stages of a Comptroller business audit and identify the points at which counsel can shape scope, sample periods, and the working-paper record.
Preserve a client's appeal rights by meeting the 30-day deadlines for an application for revision or refund claim and for an appeal to the Maryland Tax Court, and evaluate the limited relief available under Section 13-509 when a deadline is missed.